
No Doc Loans
 Written by Bill Lyons
 Reviewed by Guy Troxler


KEY TAKEAWAYS
- A no doc mortgage lets you buy a property or replace your current first mortgage using alternative documentation instead of tax returns, W-2s, or pay stubs.
- “No doc” does not mean no paperwork. Lenders still verify your ability to repay through bank statements, assets, 1099s, profit and loss statements, or rental income.
- Common no doc loan options include bank statement, asset depletion, 1099, profit and loss, and DSCR mortgages.
- The down payment, credit score, cash reserves, and maximum loan amount depend on the program, property, occupancy, and strength of the application.
- If you want to access equity without replacing your first mortgage, check out our no doc HELOC or HELOAN guide instead.
If you want to purchase a property or replace your current first mortgage, a no doc mortgage lets you qualify with financial records that better reflect how you earn money or hold wealth. These loans best serve self-employed borrowers, independent contractors, retirees, investors, and others whose finances do not fit conventional mortgage rules.
This page covers no doc mortgages used to buy or refinance a property. If you already own a home and want to borrow against its equity without replacing the first mortgage, read our guide to no doc home equity loans.
No Doc Loan Requirements at a Glance
No doc loan requirements depend on how you qualify: most Griffin Funding programs start at a 620 credit score and 10% to 20% down, with loan amounts up to $4.5 million.
| Program | Documents used to qualify | Minimum credit score | Minimum down payment | Maximum loan amount | Eligible properties |
|---|---|---|---|---|---|
| Bank statement loan | 12 or 24 months of personal or business bank statements | 620 | 10%1 | $4.5 million | Primary, second home, investment |
| 1099 loan | 1 or 2 years of 1099 forms | 620 | 10%1 | $4.5 million | Primary, second home, investment |
| Asset depletion loan | Bank, brokerage, money market, or retirement account statements | 620 | 20% | $3.5 million | Primary, second home, investment |
| Profit and loss statement loan | Business profit and loss statement for the required period | 620 | 10%1 | $4.5 million | Primary, second home, investment |
| DSCR loan | Lease or appraiser’s market rent for the property2 | 620 | 15%3 | $4.5 million; up to $20 million by exception | Investment only |
- 110% down applies to smaller loan amounts for highly qualified borrowers. Larger loans require more down; bank statement loans above $3 million require 25% down.
- 2Griffin Funding has no minimum DSCR requirement.
- 315% down requires a 740+ credit score. Most DSCR borrowers put 20% to 25% down.
- Minimums are program floors as of October 2026. Your requirements depend on credit, loan amount, property type, occupancy, and documentation.
What Is a No Doc Mortgage Loan?
A no doc mortgage is a first mortgage that finances a purchase or replaces an existing first mortgage using alternative financial documentation. Despite the name, borrowers still need to provide alternative financial documents, and for a home you will live in, lenders must make a reasonable, good-faith determination that you can repay the loan.
A non-QM mortgage allows the lender to verify income in other ways. For example, it may use 12 or 24 months of eligible bank deposits to calculate a business owner’s income instead of relying on tax returns that reflect business deductions.
How Today’s No Doc Loans Differ From Old Stated-Income Loans
The biggest difference is that today’s no doc loans still require verification. Before the 2008 financial crisis, some stated-income, stated-assets loans allowed borrowers to report their income and assets without fully proving them. That practice is now heavily restricted and generally unavailable for owner-occupied homes.
Modern no doc lenders verify the alternative documentation used to approve the loan, such as bank statements, assets, 1099s, profit and loss statements, or rental income. You may also see terms such as stated-income, verified-assets (SIVA) or no-income, verified-assets (NIVA). These labels indicate whether the lender considers borrower-reported income or qualifies the borrower primarily through verified assets.
No Doc Mortgage vs. No Doc Home Equity Loan
A no doc mortgage is a first mortgage used to buy a property or refinance an existing home loan. A no doc home equity loan or HELOC lets you borrow against your equity while keeping your current first mortgage in place.
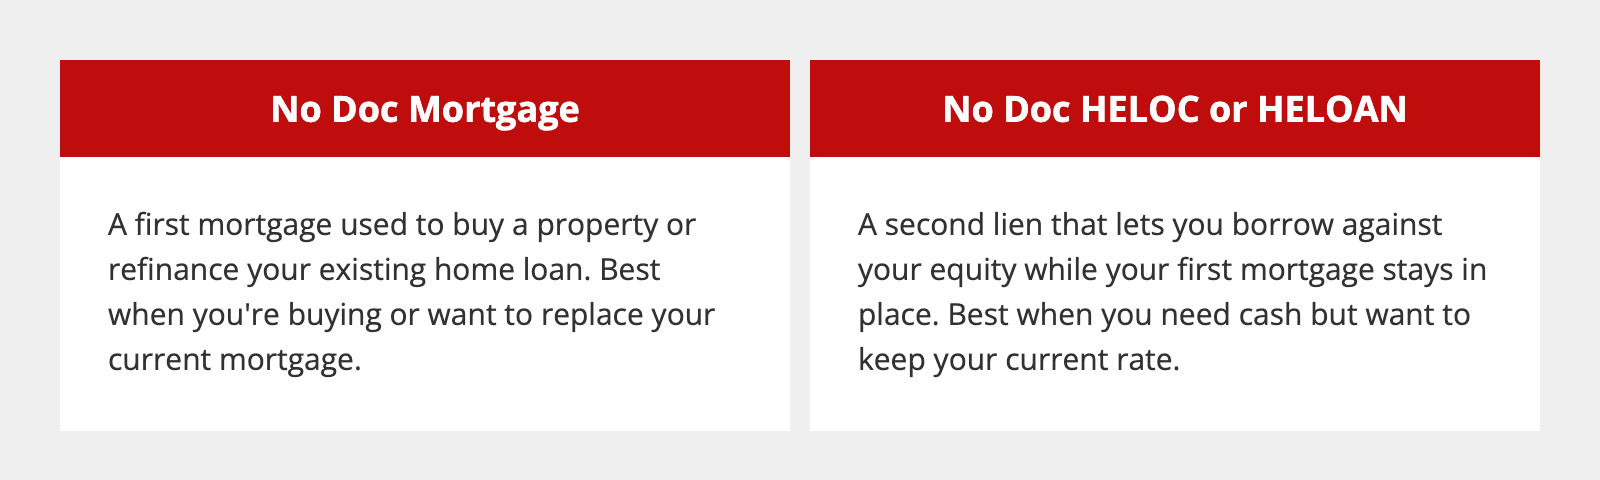
A no doc mortgage may be the better fit when you are buying a property or need to replace your current mortgage. A no doc home equity loan or HELOC may make more sense when you need cash but want to preserve the rate and terms of your existing mortgage.
| Feature | No Doc Mortgage | No Doc HELOC or HELOAN |
| Lien position | Usually the first mortgage | Usually a second mortgage |
| Can finance a home purchase | Yes | No |
| Can replace the first mortgage | Yes | No |
| How you access equity | Cash-out refinance | Second lien |
| What happens to the current mortgage | It is paid off and replaced | It remains unchanged |
| Payments after closing | One mortgage payment | First-mortgage payment plus a second-lien payment |
Who Are No Doc Loans For?
A no doc loan may be a good fit for borrowers who can afford a mortgage but cannot easily prove their ability to repay with W-2s, pay stubs, or tax returns.
They may work for:
- Self-employed professionals whose business deductions reduce taxable income
- Business owners who receive income through company deposits rather than a regular paycheck
- Freelancers, consultants, and gig workers paid on 1099s
- Borrowers with seasonal or irregular income
- Retirees and high-net-worth borrowers with substantial eligible assets
- Real estate investors who want to qualify through the property’s rental income
If your tax returns show enough income to qualify, compare a conventional loan with any government-backed programs available to you, since these options may offer lower rates and costs. A no doc mortgage is most useful when standard documents do not accurately reflect your income, assets, or rental cash flow.
Types of No Doc Mortgage Loans
No doc mortgage loans can verify your ability to repay through bank deposits, assets, 1099 income, profit and loss statements, or rental income. The right option depends on which records most accurately reflect your finances.
Bank Statement Loans
A bank statement loan uses 12 or 24 months of personal or business bank statements to calculate income instead of tax returns. The lender removes transfers and other ineligible deposits, then calculates your average monthly income.
The calculation depends on the type of account:
- Eligible personal deposits may count at or near 100%
- Business deposits are reduced by an expense factor to account for operating costs
Griffin Funding typically starts with a 50% expense ratio for business accounts. If your documented expenses are lower, the lender may use a different percentage.
Example: $30,000 in average monthly business deposits × (1 − 50% expense ratio) = $15,000 in qualifying monthly income.
Asset-Based Loans
An asset-based loan allows you to qualify using eligible assets instead of regular employment income. The lender converts funds held in qualifying bank, brokerage, money market, or retirement accounts into monthly income using an asset depletion calculation.
After accounting for any required adjustments, closing funds, and reserves, Griffin Funding divides the eligible asset balance by 60 months on most programs. This option may work well for retirees and high-net-worth borrowers who have substantial assets but limited or irregular income.
Example: $1,500,000 in eligible assets ÷ 60 months = $25,000 in qualifying monthly income.
1099 Mortgage Loans
A 1099 mortgage loan lets eligible freelancers and independent contractors qualify using one or two years of 1099 forms. Griffin Funding may count 90% to 100% of gross 1099 income, depending on the program and documentation.
“We take the gross amount and don’t need bank statements to qualify, which makes it easier on the borrower,” explains Cody Unger, Griffin Funding loan officer (NMLS #1295308).
The borrower does not need 12 or 24 months of statements for the income calculation, although statements may still be required to verify closing funds or reserves. Other requirements, including work history, credit, DTI, and down payment or equity, still apply.
Profit and Loss Statement Loans
A profit and loss statement loan uses a business’s recent revenue and expenses to establish income. The P&L generally must cover the required period and meet the program’s preparation or review standards.
This method may work well for a business with seasonal or cyclical revenue. Bank statements show when deposits arrive, so several slow months can make the borrower’s income appear less reliable than it is.
A P&L provides a broader view by showing the business’s revenue, expenses, and overall performance across the required period. As Griffin Funding loan officer Cody Unger (NMLS #1295308) explains, it “might help tell the story better to underwriting.” If your deposits fluctuate significantly from month to month, ask whether a P&L would present a more accurate picture of your business income.
DSCR Loans
A DSCR loan qualifies an eligible investment property by comparing its gross rent with its monthly housing expense rather than reviewing the borrower’s personal income.
DSCR = gross monthly rent ÷ monthly PITIA
PITIA generally includes principal, interest, taxes, insurance, and applicable association dues. A DSCR of 1.00 means the rent equals the included housing expense. DSCR loans apply to eligible non-owner-occupied properties, not primary residences.
Griffin Funding has no minimum DSCR requirement.
Which No Doc Loan Fits Your Situation?
| Your financial situation | Program to consider | What the lender reviews |
| You run a business with regular deposits | Bank statement loan | 12 or 24 months of eligible deposits |
| You have substantial liquid or retirement assets | Asset depletion mortgage | Eligible assets converted to monthly income |
| Most of your income is reported on 1099s | 1099 mortgage | One or two years of gross 1099 income |
| Your current business results are best shown on a P&L | Profit and loss statement loan | Business revenue and expenses |
| You are financing a rental property | DSCR loan | Property rent compared with housing expense |
Some borrowers qualify under more than one method. Running both calculations can show which program recognizes more income or produces the better loan terms.
Using a No Doc Loan to Purchase a Property
A no doc purchase loan becomes the property’s first mortgage. You contribute the required down payment and closing funds, but qualify with the alternative documents required by the selected program.
Down Payment Requirements
Some Griffin Funding no doc purchase programs begin at 10% down for highly qualified borrowers. The required amount can increase based on credit, loan size, property use, property type, and documentation method.
As a general guide:
- Strong bank statement and 1099 borrowers may have options starting at 10% down.
- Many no doc borrowers should expect to put down 15% to 20%.
- Second homes and investment properties commonly require 20% to 25%.
- Strong borrowers with 740+ credit score may qualify for 15% down on DSCR loans.
Why Preapproval Matters
Before you shop, ask the lender to review enough documentation to calculate a realistic loan amount. For a bank statement loan, that means checking deposits for transfers, business expenses, and other exclusions rather than relying only on the income entered on the application.
How One Couple Bought Without Two Years of Tax Returns
In 2024, a self-employed couple in Hawaii used a 12-month bank statement loan with Griffin Funding to buy their primary residence after opening a business in mid-2023. They lacked the two years of tax returns normally expected in conventional underwriting, but the eligible deposits provided enough income when Griffin credited the co-borrower’s documented 50% ownership share.
The loan did not require tax returns, but the couple still had to establish the co-borrower’s self-employment history and ownership interest. A CPA letter confirmed that she had been self-employed for at least two years, while an operating agreement documented the couple’s 50/50 ownership.
They also provided their required contribution and six months of reserves. Once Griffin verified the income, ownership, work history, and funds, the loan closed ahead of the seller’s deadline.
Using a No Doc Loan to Refinance
A no doc refinance works like any other mortgage refinance: it pays off your current first mortgage and replaces it with a new one. The difference is how you qualify. Instead of using tax returns, W-2s, or pay stubs, you may qualify with bank statements, assets, 1099s, a profit and loss statement, or rental income.
There are two main types of refinancing.
Rate-and-Term Refinance
A rate-and-term refinance replaces your current mortgage with one that has different terms. The goal is to improve the loan rather than receive cash. You might refinance to lower your interest rate or monthly payment, switch from an adjustable to a fixed rate, or shorten the repayment period so you can pay off the mortgage sooner.
Compare the expected savings with the closing costs before refinancing. A lower monthly payment may still increase your total cost if it comes from restarting the loan with a longer repayment period.
Cash-Out Refinance
A cash-out refinance replaces your current mortgage with a larger loan and gives you part of the difference in cash. The goal is to access home equity for expenses such as renovations, debt consolidation, or a major purchase while keeping everything in one mortgage.
For example, suppose your home is worth $700,000, you owe $350,000, and the program allows a new loan of $490,000:
$490,000 new mortgage − $350,000 current mortgage = up to $140,000 in cash before costs
The amount you receive will be lower after closing costs and any other required payments are deducted.
The new interest rate applies to the entire $490,000 mortgage, not only the $140,000 you receive. If your current mortgage has a much lower rate, compare the refinance with a no doc HELOC or HELOAN, which lets you borrow against your equity without replacing your first mortgage.
No Doc Loan Requirements
No doc loans change how lenders verify income. They do not eliminate other underwriting requirements, such as credit, existing debts, down payment or equity, cash reserves, mortgage payment history, and property eligibility. Exact requirements vary by loan program and how you qualify.
Credit Score
Most no doc loans require borrowers to have a 700+ credit score, though some Griffin Funding no doc programs accept credit scores starting around 620. Borrowers seeking the smallest down payment, highest loan-to-value ratio, or best pricing generally need stronger credit. A 90% LTV option may require a score closer to 700 or 720, depending on the program.
Griffin Funding also reviews recent mortgage payments, revolving balances, delinquencies, bankruptcies, foreclosures, and the depth of the credit history.
Income or Assets
Griffin Funding will verify your ability to repay using the alternative documents required by your loan program. Depending on how you qualify, you may need to provide complete 12 or 24 months of bank statements, one or two years of 1099s, statements showing eligible assets, a qualifying profit and loss statement, or rental income documents for a DSCR loan.
Submit every requested page and explain any large deposits or transfers. Missing pages, unexplained deposits, and conflicting information can slow the review or reduce the amount of income Griffin Funding can count.
Work or Business History
Many no doc programs look for a two-year history of self-employment or similar work. Griffin Funding may consider one year in business when the borrower also has prior experience in the same field. The exact requirement depends on the program and whether the documented income appears stable and likely to continue.
Debt-to-Income Ratio
Bank statement, asset depletion, 1099, and P&L programs generally use a debt-to-income ratio. DTI compares monthly debt payments with the monthly income established through the alternative calculation.
DTI = total monthly debt payments ÷ qualifying monthly income
Griffin Funding programs may allow DTI around 50%, with some scenarios reaching 55%. The maximum depends on the full application. DSCR loans are different because approval centers on the rental property’s cash flow rather than the borrower’s personal DTI.
Cash Reserves
Griffin Funding may require you to have enough money left after closing to cover several months of mortgage payments. The exact amount depends on the loan program and details such as your credit, loan amount, property, and overall application.
Griffin Funding measures reserves in months of mortgage payments. Depending on the program, that payment may include principal, interest, property taxes, homeowners insurance, and applicable association dues. Reserve funds are separate from the money needed for your down payment and closing costs.
Property Value and Eligibility
An appraisal or other approved valuation confirms the property’s market value. The property must also meet the program’s occupancy, condition, type, and location requirements.
For a DSCR loan, the lender will document market rent or current lease income in addition to property value.
No Doc Mortgage Rates and Costs
No doc mortgage rates are usually higher than comparable conventional rates because the lender is using alternative documentation and taking on a different risk profile. The difference is not fixed.
Less Documentation Can Mean Higher Costs
Most no doc loans still verify income using bank statements, 1099s, a P&L, or rent. A no-income-verification loan goes a step further by qualifying you without using income, often relying on verified assets, credit, and equity instead. Because the lender has less financial information to review, the loan may have a higher rate, more fees, or a lower borrowing limit. For an owner-occupied mortgage, the lender must still determine that you can repay the loan.
One self-employed homeowner initially considered this type of loan for a cash-out refinance on his primary residence. The available structure limited cash-out to approximately 75% LTV and carried substantially higher pricing, so his Griffin Funding loan officer advised him to compare other qualification methods.
Because the borrower owned his business outright and could provide 12 months of business bank statements, Griffin Funding qualified him through a bank statement program instead. The additional documentation helped him secure better pricing without the tighter cash-out limit. The takeaway is simple: a borrower who can document sufficient deposits may receive more favorable terms than one using the least-documentation option.
What Affects Your No Doc Mortgage Rate
Pricing depends on:
- Credit score
- Down payment or equity
- Loan amount
- Property type and occupancy
- Income-documentation method
- DTI or DSCR
- Cash reserves
- Fixed, adjustable, or interest-only structure
- Points paid at closing
Interest-only is a payment feature, not a type of no doc loan. It may be available with certain programs, but the loan still qualifies through bank statements, assets, 1099s, a P&L, or DSCR.
Compare the interest rate, annual percentage rate, lender fees, points, monthly payment, and total cash required to close. Investment-property loans may also include a prepayment penalty, depending on state law and the selected terms.
Benefits and Drawbacks of No Doc Loans
Benefits
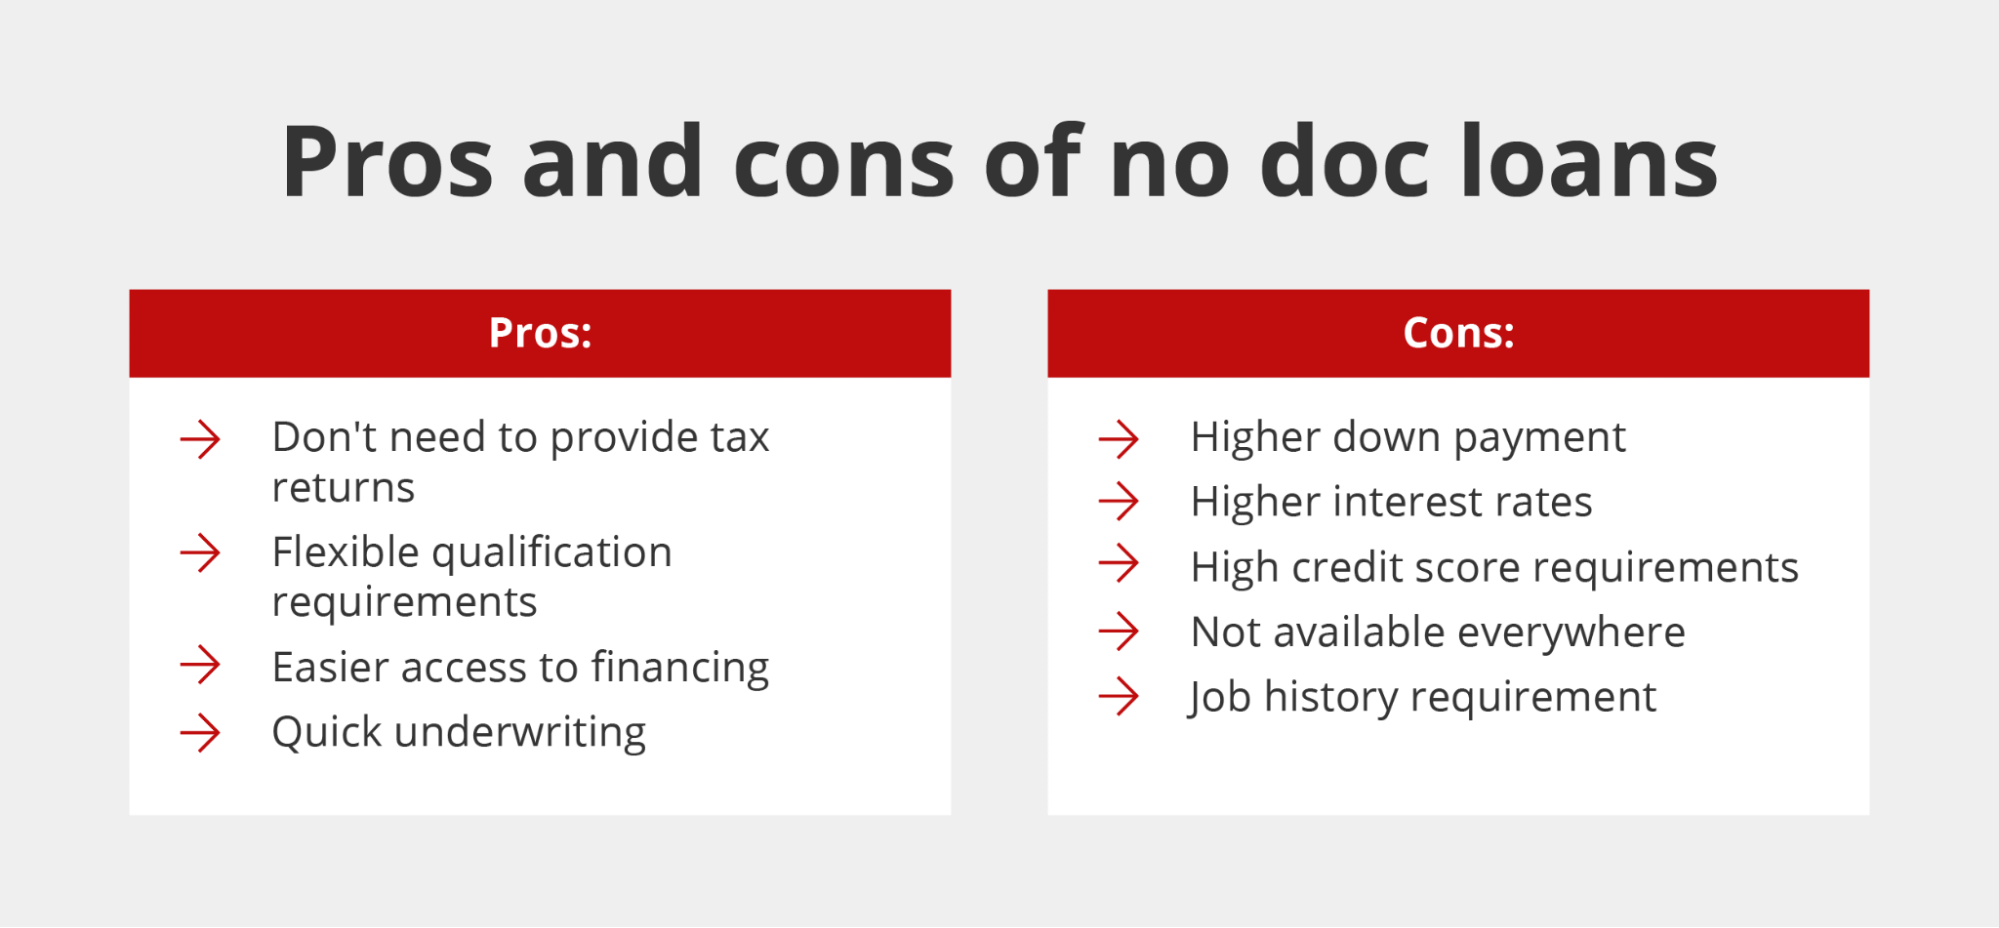
- You may qualify without tax returns, W-2s, or pay stubs.
- The lender can use records that better reflect current cash flow or wealth.
- Programs are available for primary residences, second homes, and investment properties.
- You can use the loan for a purchase, rate-and-term refinance, or cash-out refinance.
- High-balance financing may be available beyond conventional loan limits.
Drawbacks
- Rates and fees may be higher than conventional financing.
- You may need a larger down payment or more equity.
- Reserve requirements can leave more cash tied up after closing.
- Alternative-documentation calculations can be detailed and program-specific.
- Not every lender offers or understands these loans.
Instead of comparing no doc and conventional loans in general, compare the specific offers available to you. Look at the monthly payment, cash needed at closing, fees, and total long-term cost.
How to Get a No Doc Loan
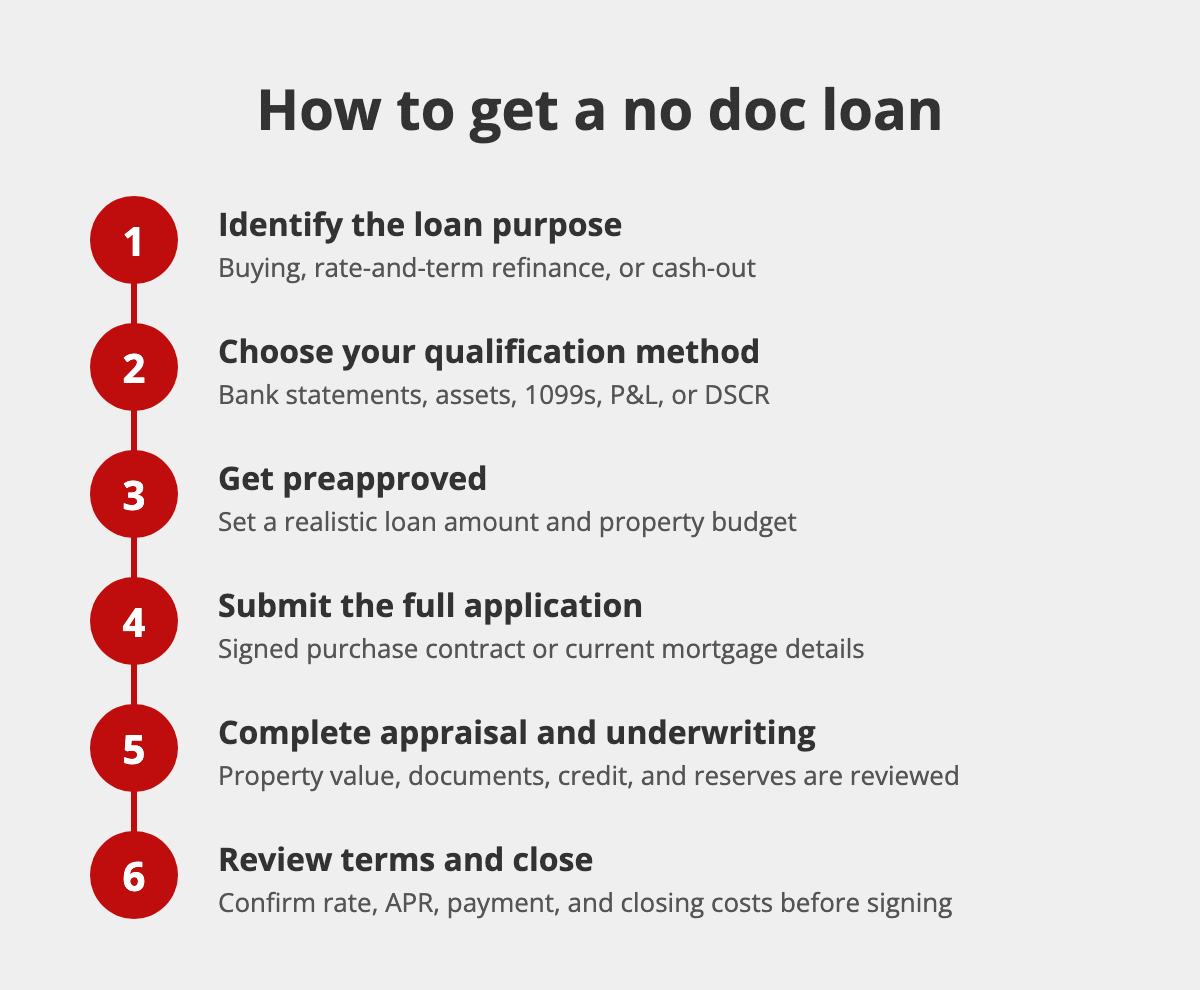
1. Identify the Loan Purpose
Decide whether you are buying a property, completing a rate-and-term refinance, or taking cash out. This determines the LTV calculation and documentation the lender will request.
2. Choose the Strongest Qualification Method
Compare bank statements, assets, 1099s, a P&L, and DSCR when more than one option applies. The method that requires the fewest documents is not always the one that produces the most qualifying income.
3. Get Preapproved
Provide the core documents needed for a meaningful calculation. For a purchase, the preapproval should state a realistic loan amount and help you set the property budget.
4. Submit the Property and Full Application
For a purchase, provide the signed contract after your offer is accepted. For a refinance, provide the current mortgage statement, property information, and requested payoff details.
5. Complete the Appraisal and Underwriting
Griffin Funding confirms the property value, reviews the selected alternative documentation, and checks credit, debts, funds to close, reserves, and program eligibility.
6. Review the Terms and Close
Compare the final loan terms with the original quote. Confirm the interest rate, APR, payment, cash required, prepayment terms, and closing costs before signing.
Where Can You Get a No Doc Loan?
Not every bank or mortgage lender offers no doc loans because these programs require specialized non-QM underwriting. Griffin Funding specializes in this type of financing, with options for self-employed borrowers, high-net-worth borrowers, and real estate investors. We are a direct-to-consumer lender licensed in 47 states and Washington, D.C.
Our loan officers can review your income, assets, and goals to identify the Griffin Funding program that fits your situation. We will explain which documents you need, how your qualifying income is calculated, and what to expect before closing.
See If You Qualify for a No Doc Mortgage
Your income does not need to arrive as a predictable paycheck to support a mortgage. Griffin Funding works with self-employed borrowers, contractors, retirees, and real estate investors to identify the documentation that presents their finances accurately.
Whether you want to purchase a property or replace your current first mortgage, a loan officer can compare the available bank statement, asset depletion, 1099, P&L, and DSCR options and show you how each one affects your qualifying amount and terms.
Apply for a no doc loan or call 855-698-1098 to discuss your purchase or refinance.
Find the best loan for you. Reach out today!
Get StartedFrequently Asked Questions
Can I get a mortgage with no documents at all? 
Can I use a no doc loan to buy a primary residence?
Can I refinance with a no doc mortgage?
Does a no doc refinance leave my current mortgage in place?
How many bank statements do I need?
What credit score do I need for a no doc loan?
How much do I need for a down payment?
Can I qualify if I am not currently employed?
Are no doc mortgage rates higher?
Can I get a no doc loan for an investment property?
Is a no doc loan the same as a low doc loan?
What is the maximum loan amount for a no doc mortgage?

Bill Lyons is the Founder, CEO & President of Griffin Funding. Founded in 2013, Griffin Funding is a national boutique mortgage lender focusing on delivering 5-star service to its clients. Mr. Lyons has 25 years of experience in the mortgage business. Lyons is seen as an industry leader and expert in real estate finance. Lyons has been featured in Forbes, Inc., Wall Street Journal, HousingWire, and more. As a member of the Mortgage Bankers Association, Lyons is able to keep up with important changes in the industry to deliver the most value to Griffin's clients. Under Lyons' leadership, Griffin Funding has made the Inc. 5000 fastest-growing companies list six times in its 13 years in business. Follow his updates on LinkedIn.
 Outstanding Client Experience
 Specialized Lending Solutions
 Direct-to-Consumer Advantage
 We're Advisors, NOT Salespeople
 Effortless Digital Mortgage Platform
Featured In

Recent Posts
Mortgage rates hit 18% in 1981. Here’s how that compares with buying a home today
Borrowers shopping for a 30-year fixed mortgage in the fall of 1981 saw rates peak at 18.63% in the week of Oc...

Average home equity gains topped $200,000 in six states as renters faced heavy housing costs
A rising home value can mean two very different things on the same street. For an established homeowner, it ca...
A 1-percentage-point mortgage rate rise can outrun 4 years of rent growth
The Federal Reserve raised interest rates on Sept. 16 for the first time since 2023. For rental property inves...